AskJoe.

02First-time buyer HQ

Good news: that’s the normal starting point, and it’s completely fixable. This page retires the myths, walks the real steps, and shows you the Minnesota programs built specifically for you.

Myth-busting, part one

Each of these has stopped real buyers from even trying. None of them survive contact with the facts.

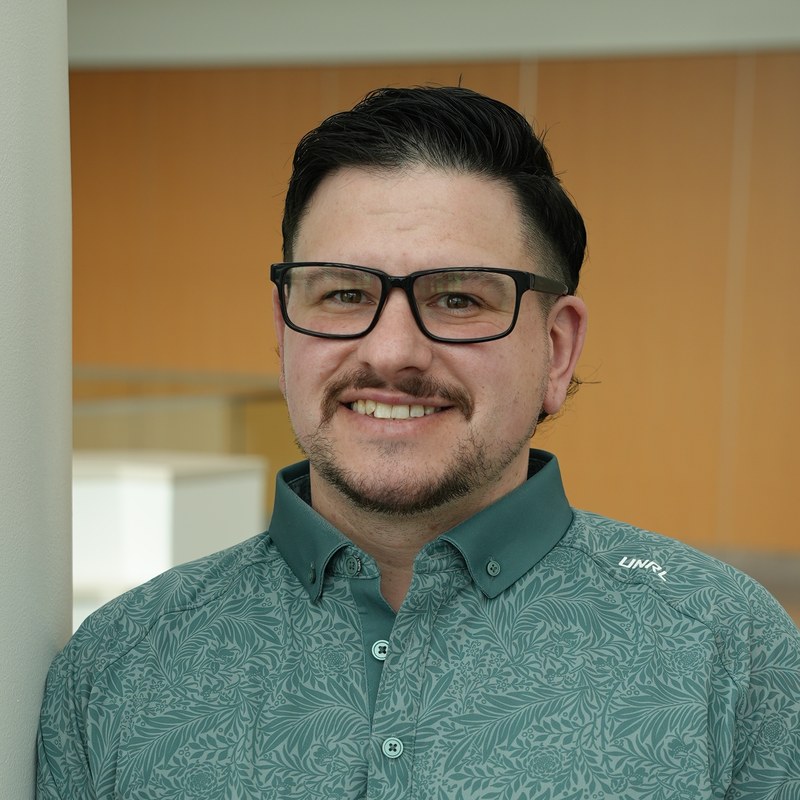
Joe · Loan Officer
is it dumb that I don’t even know where to start? 😅
Not even a little — nobody is born knowing this stuff. Give me 15 minutes and you’ll know your starting point, your budget, and your next step. That’s it.
You need 20% down to buy a home

The truth: Conventional and FHA loans have low down payment options for qualified buyers, and VA and USDA don’t require one for eligible borrowers. 20% down only means one thing: no mortgage insurance. It has never been the price of admission.

Your credit has to be perfect

The truth: Conventional programs generally start around a 620 score and FHA can go lower. Better scores get better pricing, but "perfect" has never been the requirement — and Joe can point you toward realistic ways to strengthen your score before you apply.

You should wait for rates to drop

The truth: Nobody can time rates — not Joe, not the news, not the internet. What you can control: buying a home that fits your budget at today's numbers. If rates drop later, refinancing exists. If they rise, you're glad you didn't wait.

Getting pre-approved hurts your credit

The truth: A mortgage pre-approval is a single hard inquiry — typically a few points, temporarily. Credit scoring models also treat multiple mortgage inquiries within a shopping window as one. The insight you gain massively outweighs the ding.

Find the house first, then figure out financing

The truth: Backwards. Sellers take offers with pre-approval letters seriously; without one you're shopping blind and could fall in love with a house outside your real budget. The financing conversation is step one, and it's free.

Student loans mean you can't buy

The truth: Student debt factors into your debt-to-income ratio — it doesn't disqualify you. Millions of buyers with student loans close every year. Joe can show you exactly how your loans are counted and what price range they support.

The actual roadmap

Every first-time buyer walks the same six steps. Knowing the order takes most of the stress out of it.

See every phase →
1

The conversation

Text or call Joe. Fifteen minutes, plain English, no documents needed yet. You'll leave knowing your realistic starting point.

2

Pre-approval

Joe verifies income, assets and credit through Fairway's secure system and issues a pre-approval letter — the document that makes sellers take your offer seriously.

3

Set the real budget

Approved-for and comfortable-with are different numbers. Joe helps you find the monthly payment that fits your actual life.

4

Shop with confidence

You and your agent tour homes knowing exactly what works. Joe stays on call for payment math on any address you're considering.

5

Offer & contract

Offer accepted! Joe locks your file into motion — appraisal ordered, documentation gathered, underwriting begins.

6

Clear to close

Underwriting signs off, you review final numbers days before closing, then sign, get keys, and become a homeowner.

Joe · Loan Officer
wait, the state will actually help with my down payment??
Yep — Minnesota Housing has programs designed exactly for first-time buyers. Deferred loans, closing cost help, the works. Eligibility is the catch, and checking yours takes me minutes.

Minnesota-specific help

Minnesota Housing, the state’s housing finance agency, offers down payment and closing cost loans to eligible first-time buyers — often structured as deferred loans you don’t repay until you sell or refinance. Income limits, purchase price limits, and a homebuyer education course apply.

Joe works with these programs and can tell you in one conversation whether you qualify and what it would actually change about your numbers.

Minnesota Housing programs

You can only access these through a participating lender. Joe was recognized by Minnesota Housing as a 2024 Top Producing Loan Officer for doing exactly that.

First mortgage

1st

Start Up Program

Minnesota Housing's flagship first-time buyer program: a competitive fixed-rate first mortgage that unlocks the downpayment and closing cost loans below. For buyers who haven't owned a principal residence in the last three years. Income and purchase price limits apply.

Down payment + closing costs

Up to$18,000

Monthly Payment Loan

A second loan repaid in monthly installments alongside your mortgage, at the same interest rate as your first mortgage. Available with Start Up — and with Step Up if you're not a first-time buyer.

Down payment + closing costs

Up to$18,0000% interest

Deferred Payment Loans

No monthly payment and no interest: the Deferred Payment Loan (up to $16,500) and Deferred Payment Loan Plus (up to $18,000) are repaid only when you sell, refinance, or pay off your mortgage. DPL+ has additional eligibility criteria.

First-generation buyers

Up to$35,000Forgivable

First-Generation Homebuyer Loan

If you and your parents have never owned a home (or lost one to foreclosure), this deferred, interest-free loan is forgiven over time — half after 10 years, the rest after 20 — while you live in the home. Requires a Start Up first mortgage. Funds are limited and first-come, first-served.

*Program terms, amounts, income and purchase price limits are set by Minnesota Housing, are subject to change and fund availability, and require borrower eligibility including credit requirements and homebuyer education. Assistance may be structured as a loan that must be repaid. Minnesota Housing is not affiliated with Fairway Independent Mortgage Corporation. Contact Joe for current program details.

The money questions

How much money do I actually need to buy my first home in Minnesota?

Less than most people think. Between low-down-payment programs and Minnesota Housing down payment assistance, many first-time buyers close with a total cash outlay far below the mythical 20%. Closing costs typically add 2–3% of the loan amount, and some can be negotiated or credited. Joe can map your exact number in one conversation.

What credit score do I need to buy a house?

Conventional loans generally start around 620, FHA can work from 580 (sometimes lower with more down), and VA has no official minimum. Higher scores earn better pricing, so if you're close to a threshold, Joe can suggest specific moves before you apply.

What is down payment assistance and do I qualify?

Minnesota Housing offers down payment and closing cost loans to eligible buyers, often structured as a deferred second loan repaid when you sell or refinance. Qualification depends on income, purchase price, and homebuyer education. Joe works with these programs and can check your eligibility quickly.

How long does buying a first home take?

Pre-approval can happen within a day or two of submitting documents. House hunting is up to you and the market. Once you're under contract, closing typically runs about 30–45 days. From first text to keys, many first-time buyers finish in 2–4 months.

Should I pay off all my debt before buying?

Not necessarily. Lenders look at your debt-to-income ratio, not whether debt exists. Sometimes paying off a specific account helps qualification substantially; other times that cash serves you better as a down payment. This is exactly the kind of math Joe runs for free.

More on the full FAQ and in the plain-English glossary.

Start here

No documents, no commitment, no pressure — just a first conversation about where you stand and what’s possible. Text Joe at 651-245-4963 whenever you’re ready.

Text Joe · 651-245-4963 →Apply with Joe at Fairway

Applications happen on Fairway's secure site — never here.